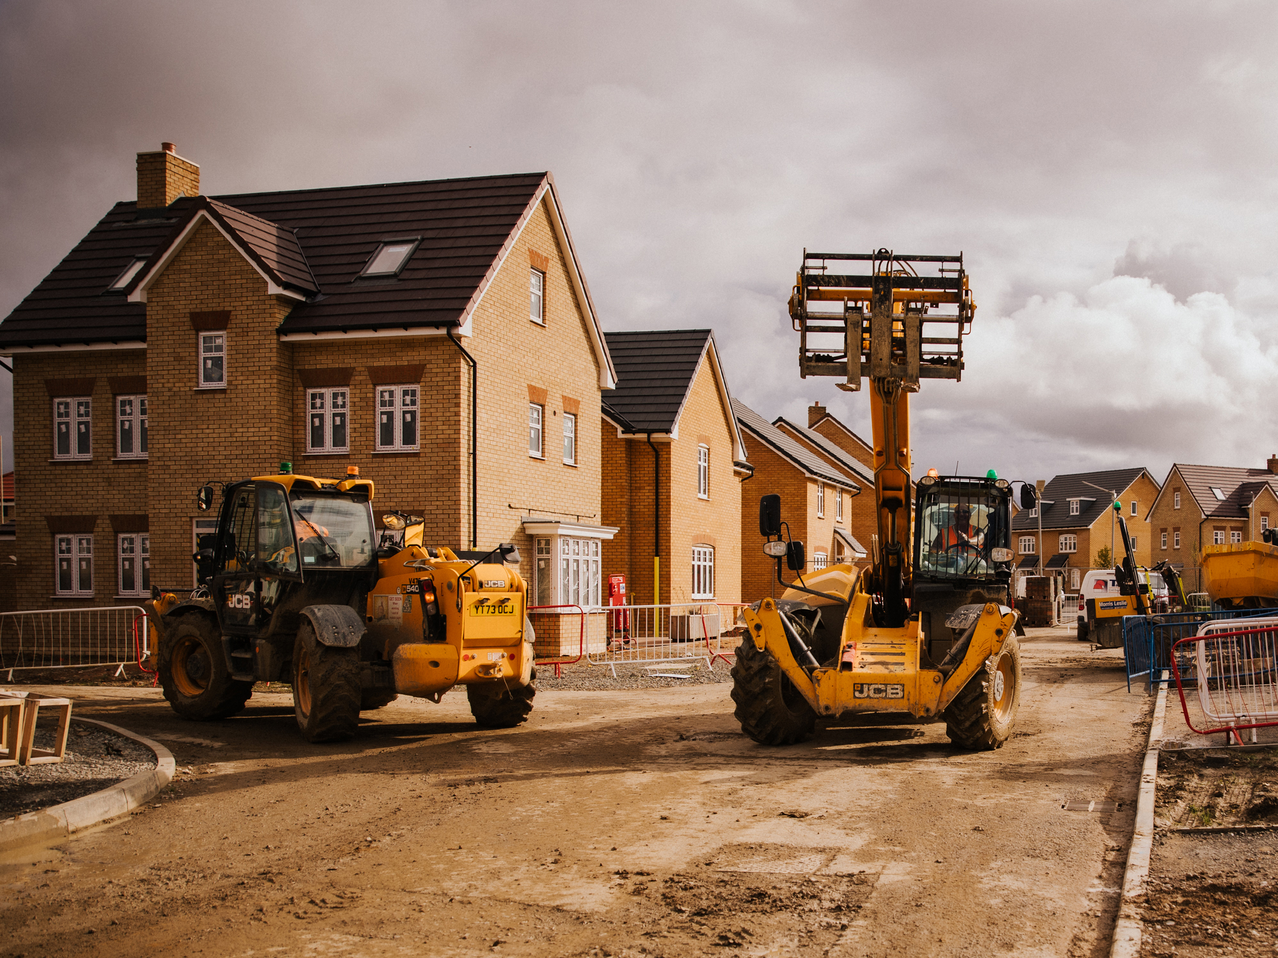
The National House Building Council (NHBC) reports that developers registered 29,162 new homes for construction in Q2 2026. This is down 4% on Q2 2025.
In a quarter marked by mounting cost pressures and geopolitical uncertainty, private sector registrations fell 5% to 19,045, compared to 20,097 in Q2 2025. Developers registered 10,117 new homes in the rental and affordable sector, compared with 10,162 in the second quarter of 2025.
Daniel Pearce, Chief Strategy Officer at NHBC explains, “Elevated interest rates, geopolitical volatility and rising costs combined with affordability pressures impacting consumer demand, meant that many house builders slowed their build programmes in the second quarter.
“While the decline in new home registrations will come as little surprise, we welcome the commitment from new Prime Minister Andy Burnham to roll out the most ambitious council house-building programme since the post-war era. This will be an important lever in boosting overall supply. Greater clarity on the mechanisms and funding will be welcomed by the industry. House builders stand ready to play their part.
“Accelerating planning reform and easing regulatory burdens would also help boost housing supply. On top of this, measures to improve affordability for prospective buyers are essential to unlocking demand.”
Regional picture remains mixed
Across the UK, 6 out of 12 regions saw a decline in registrations in Q2 2026 compared to Q2 2025. The South West recorded the steepest decline, down 42%, followed by the East Midlands (-36%) and Wales(-34%). London saw the greatest rise (+170%), with the North West (+37%), East of England (+15%), South East (+12%), West Midlands (+7%) and Scotland (+6%) also experiencing an uplift.
An increase in London registrations may offer some encouragement for the capital’s house-building market.
Daniel Pearce, Chief Strategy Officer at NHBC cautions, “Registration volumes in London are often more volatile than elsewhere in the country. Large developments frequently registered over short periods rather than evenly throughout the year. This reflects the prevalence of large, high-density schemes, which typically involve longer planning and delivery timelines before substantial volumes of units are brought forward and registered. This creates more pronounced peaks of activity. The next two quarters of NHBC data should provide a clearer indication of whether this upward trend for London is sustained.”